Walmart Spent $22.6 Billion on Capex. Is Its New Profit Mix Paying for It?
Walmart’s advertising, membership and ecommerce businesses are growing faster than store sales, but the omnichannel build is consuming more cash. The question is whether the changing mix can earn an adequate return.
 Wealth / The Compound journal
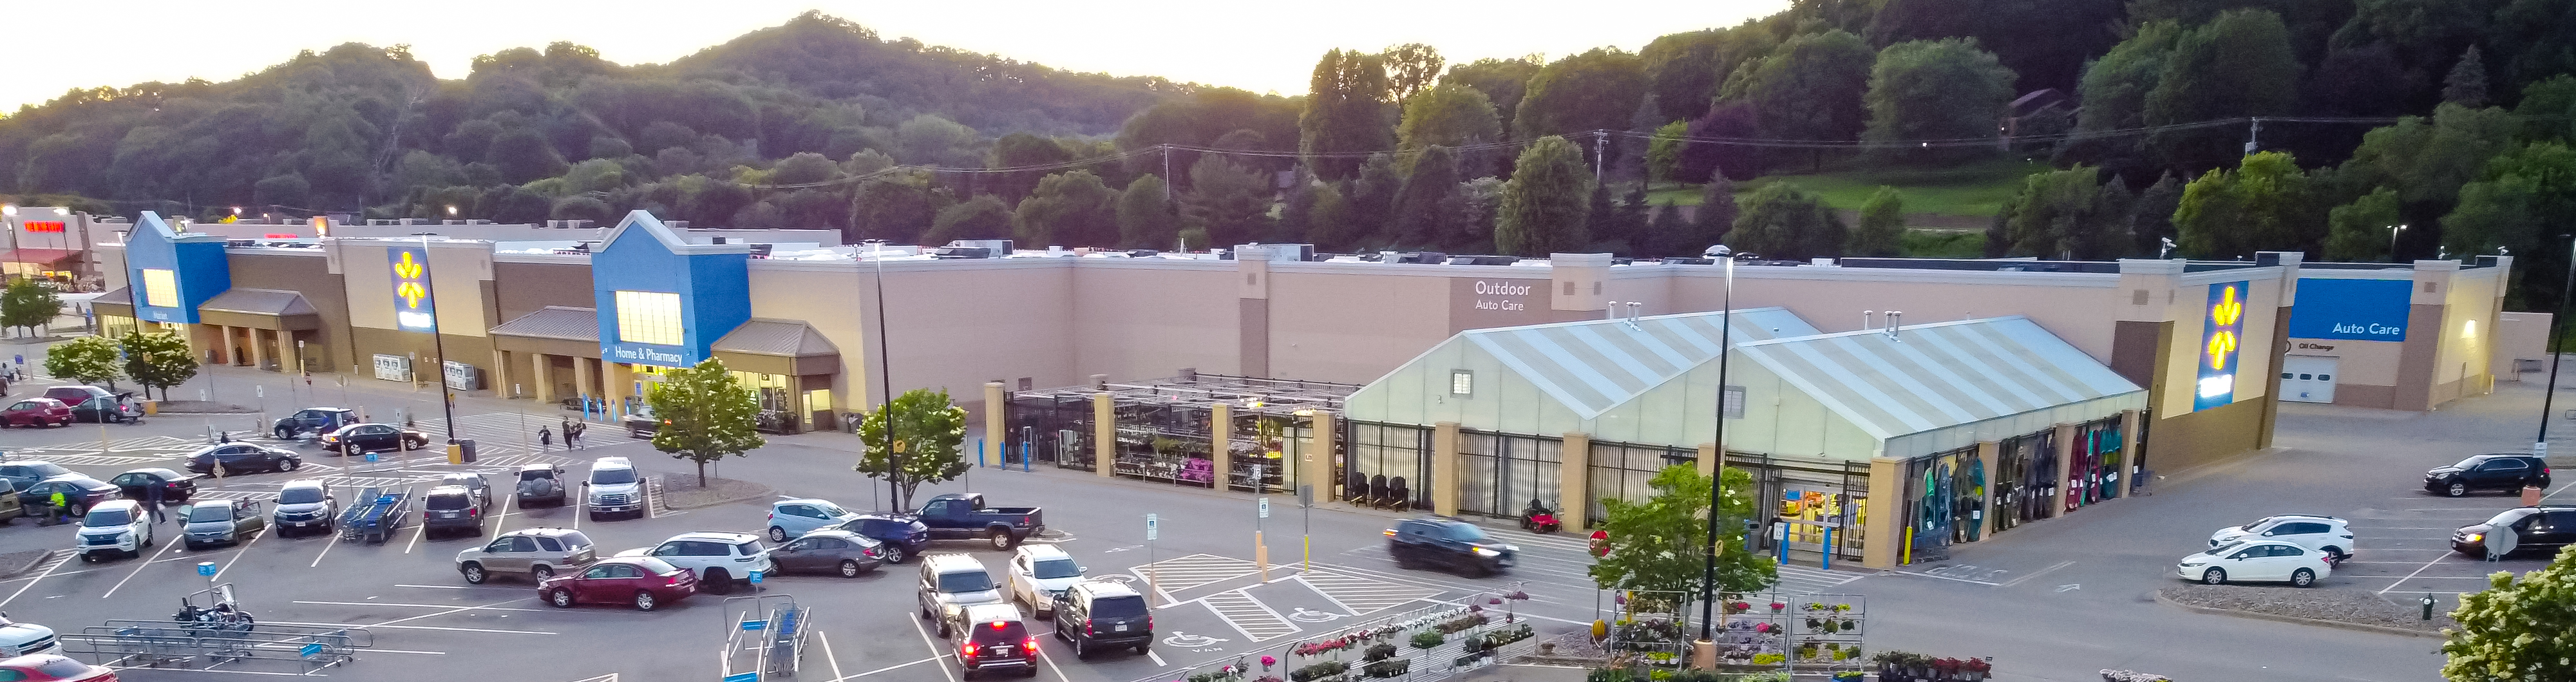
Photo: Wikideas1 / Wikimedia Commons, CC0 1.0. Archival photograph captured 8 June 2024; cropped and resized for publication. · Illustrative image.
Walmart is trying to turn its enormous store and fulfilment network into more than a low-margin retail machine. Advertising, membership and ecommerce are growing faster than total sales. The cost of building that system is also becoming harder to ignore.
For the nine months ended 31 October 2026, Walmart generated $29.4 billion of operating cash flow and spent $22.6 billion on property and equipment. Its non-GAAP free cash flow fell to $6.8 billion from $8.8 billion even though operating cash flow increased.
That creates the investment question: can faster-growing, potentially higher-return activities improve Walmart’s economics enough to justify an omnichannel capital programme that absorbed roughly 77% of operating cash flow during the period?
For the maintained quarterly record, see Walmart’s stock profile. This article focuses on the mix shift and the cash required to support it.
The growth engines are not the checkout tills
Third-quarter total revenue increased 5.2% to $188.8 billion. Inside that result, global ecommerce sales grew 17%, global advertising grew 25% and global membership-fee revenue grew 17%.
The US figures were stronger: ecommerce sales increased 23% and advertising increased 37%. Membership and other income, the GAAP line that includes more than membership fees, increased 20.3% to $2.08 billion.
These measures are not directly comparable. Ecommerce growth describes sales made through a channel, advertising is a business sold to suppliers and merchants, and membership fees are recognised over time. Walmart also does not disclose a separate operating margin for each activity.
Still, the direction matters. A retailer that earns fees from advertisers, marketplace sellers and members can generate more gross profit from the same customer relationship. The stores then serve as both shopping locations and local fulfilment assets.
The strongest version of the thesis is not simply “online sales are rising”. It is that the physical network lowers delivery costs while advertising and fees add revenue that does not require Walmart to own and resell an equivalent amount of inventory.
Guidance says profit should outgrow sales
Walmart now expects fiscal 2027 net sales to increase 4.9% to 5.2% in constant currency. Adjusted operating income is expected to increase 8.0% to 8.6% on the same basis.
At the midpoints, adjusted operating-income growth would exceed sales growth by about 3.3 percentage points. That spread is a useful test of whether the mix is improving rather than merely making Walmart larger.
The quarter itself needs care. GAAP operating income rose 16% to $7.77 billion, while adjusted operating income increased 5.5% in constant currency. Investment gains, restructuring and other adjustments make the headline GAAP comparison a poor stand-alone measure of the underlying mix.
Gross margin increased by 0.28 percentage points, led by Walmart US. That is supportive, but a single quarter cannot show whether advertising, membership and marketplace economics will permanently offset delivery, labour and technology costs.
The cash bill rose faster than cash from operations
Capital expenditure increased $3.99 billion, or about 21%, from the comparable nine-month period. Operating cash flow increased $1.98 billion, or about 7%. The result was a 23% decline in free cash flow under Walmart’s definition.
Management attributes the heavier spending to the omnichannel growth strategy. Annual guidance now places capital expenditure at approximately 4% of net sales, up from an original expectation of about 3.5%.
That spending can be productive. Automated distribution, store fulfilment and technology may lower the cost of each order and support faster delivery. They can also create capacity before demand is certain. A large installed network brings depreciation, maintenance and operating costs even when utilisation disappoints.
The relevant comparison is therefore not capex against sales alone. Investors need to see whether incremental operating profit and cash flow eventually rise faster than the asset base supporting them.
Ecommerce needs an economic, not just a sales, test
Store-fulfilled delivery led global ecommerce growth. That is strategically important because Walmart can use inventory and labour already close to customers. It does not prove that every delivered order earns an attractive margin.
Picking individual items, handling substitutions and transporting small baskets all cost money. Advertising and membership income may subsidise some of that convenience, but the public results do not provide a complete channel profit-and-loss statement.
The best evidence would be sustained operating leverage alongside ecommerce growth, without working capital or capital spending continuing to absorb a rising share of cash. If profit growth depends on permanently escalating investment, the apparent mix advantage would be less valuable.
What would confirm the thesis?
The constructive case would show adjusted operating income continuing to outgrow sales, free cash flow recovering after the current build, and advertising and membership growth remaining strong without weaker customer value. Stable inventory relative to sales would add confidence that the network is becoming more efficient.
The case would weaken if ecommerce stays fast but gross margin stalls, if capex remains near current levels without a cash-flow payoff, or if advertising growth slows as the comparison base rises. Walmart can gain share and still produce disappointing returns if too much capital is required for each additional dollar of profit.
Walmart’s emerging profit mix is strategically credible. The next test is whether the company can convert that mix into cash after funding the infrastructure that makes it possible. A view on the shares also requires a current valuation and explicit assumptions; this analysis makes no price target.
Explore Compound’s earnings hub and our guide to investment diversification.
Reported figures are in US dollars and relate to Walmart’s fiscal 2027 third quarter or the nine months ended 31 October 2026, as stated. Free cash flow and adjusted operating income are non-GAAP measures. Facts come from Walmart’s results release, presentation and Form 8-K; interpretation and rounded calculations are Compound’s. General information, not personal investment advice.
Cover: Wikideas1, Wikimedia Commons, under CC0 1.0. Captured 8 June 2024 in Onalaska, Wisconsin. Cropped and resized for publication; archival image.