Was Tesla's Cybertruck a Failure? The Numbers Behind the Wind-Down
Cybertruck's sales point to a commercial disappointment. But the viral claim that Tesla lost exactly $1.9 billion goes beyond what its accounts disclose.
 News / Wealth
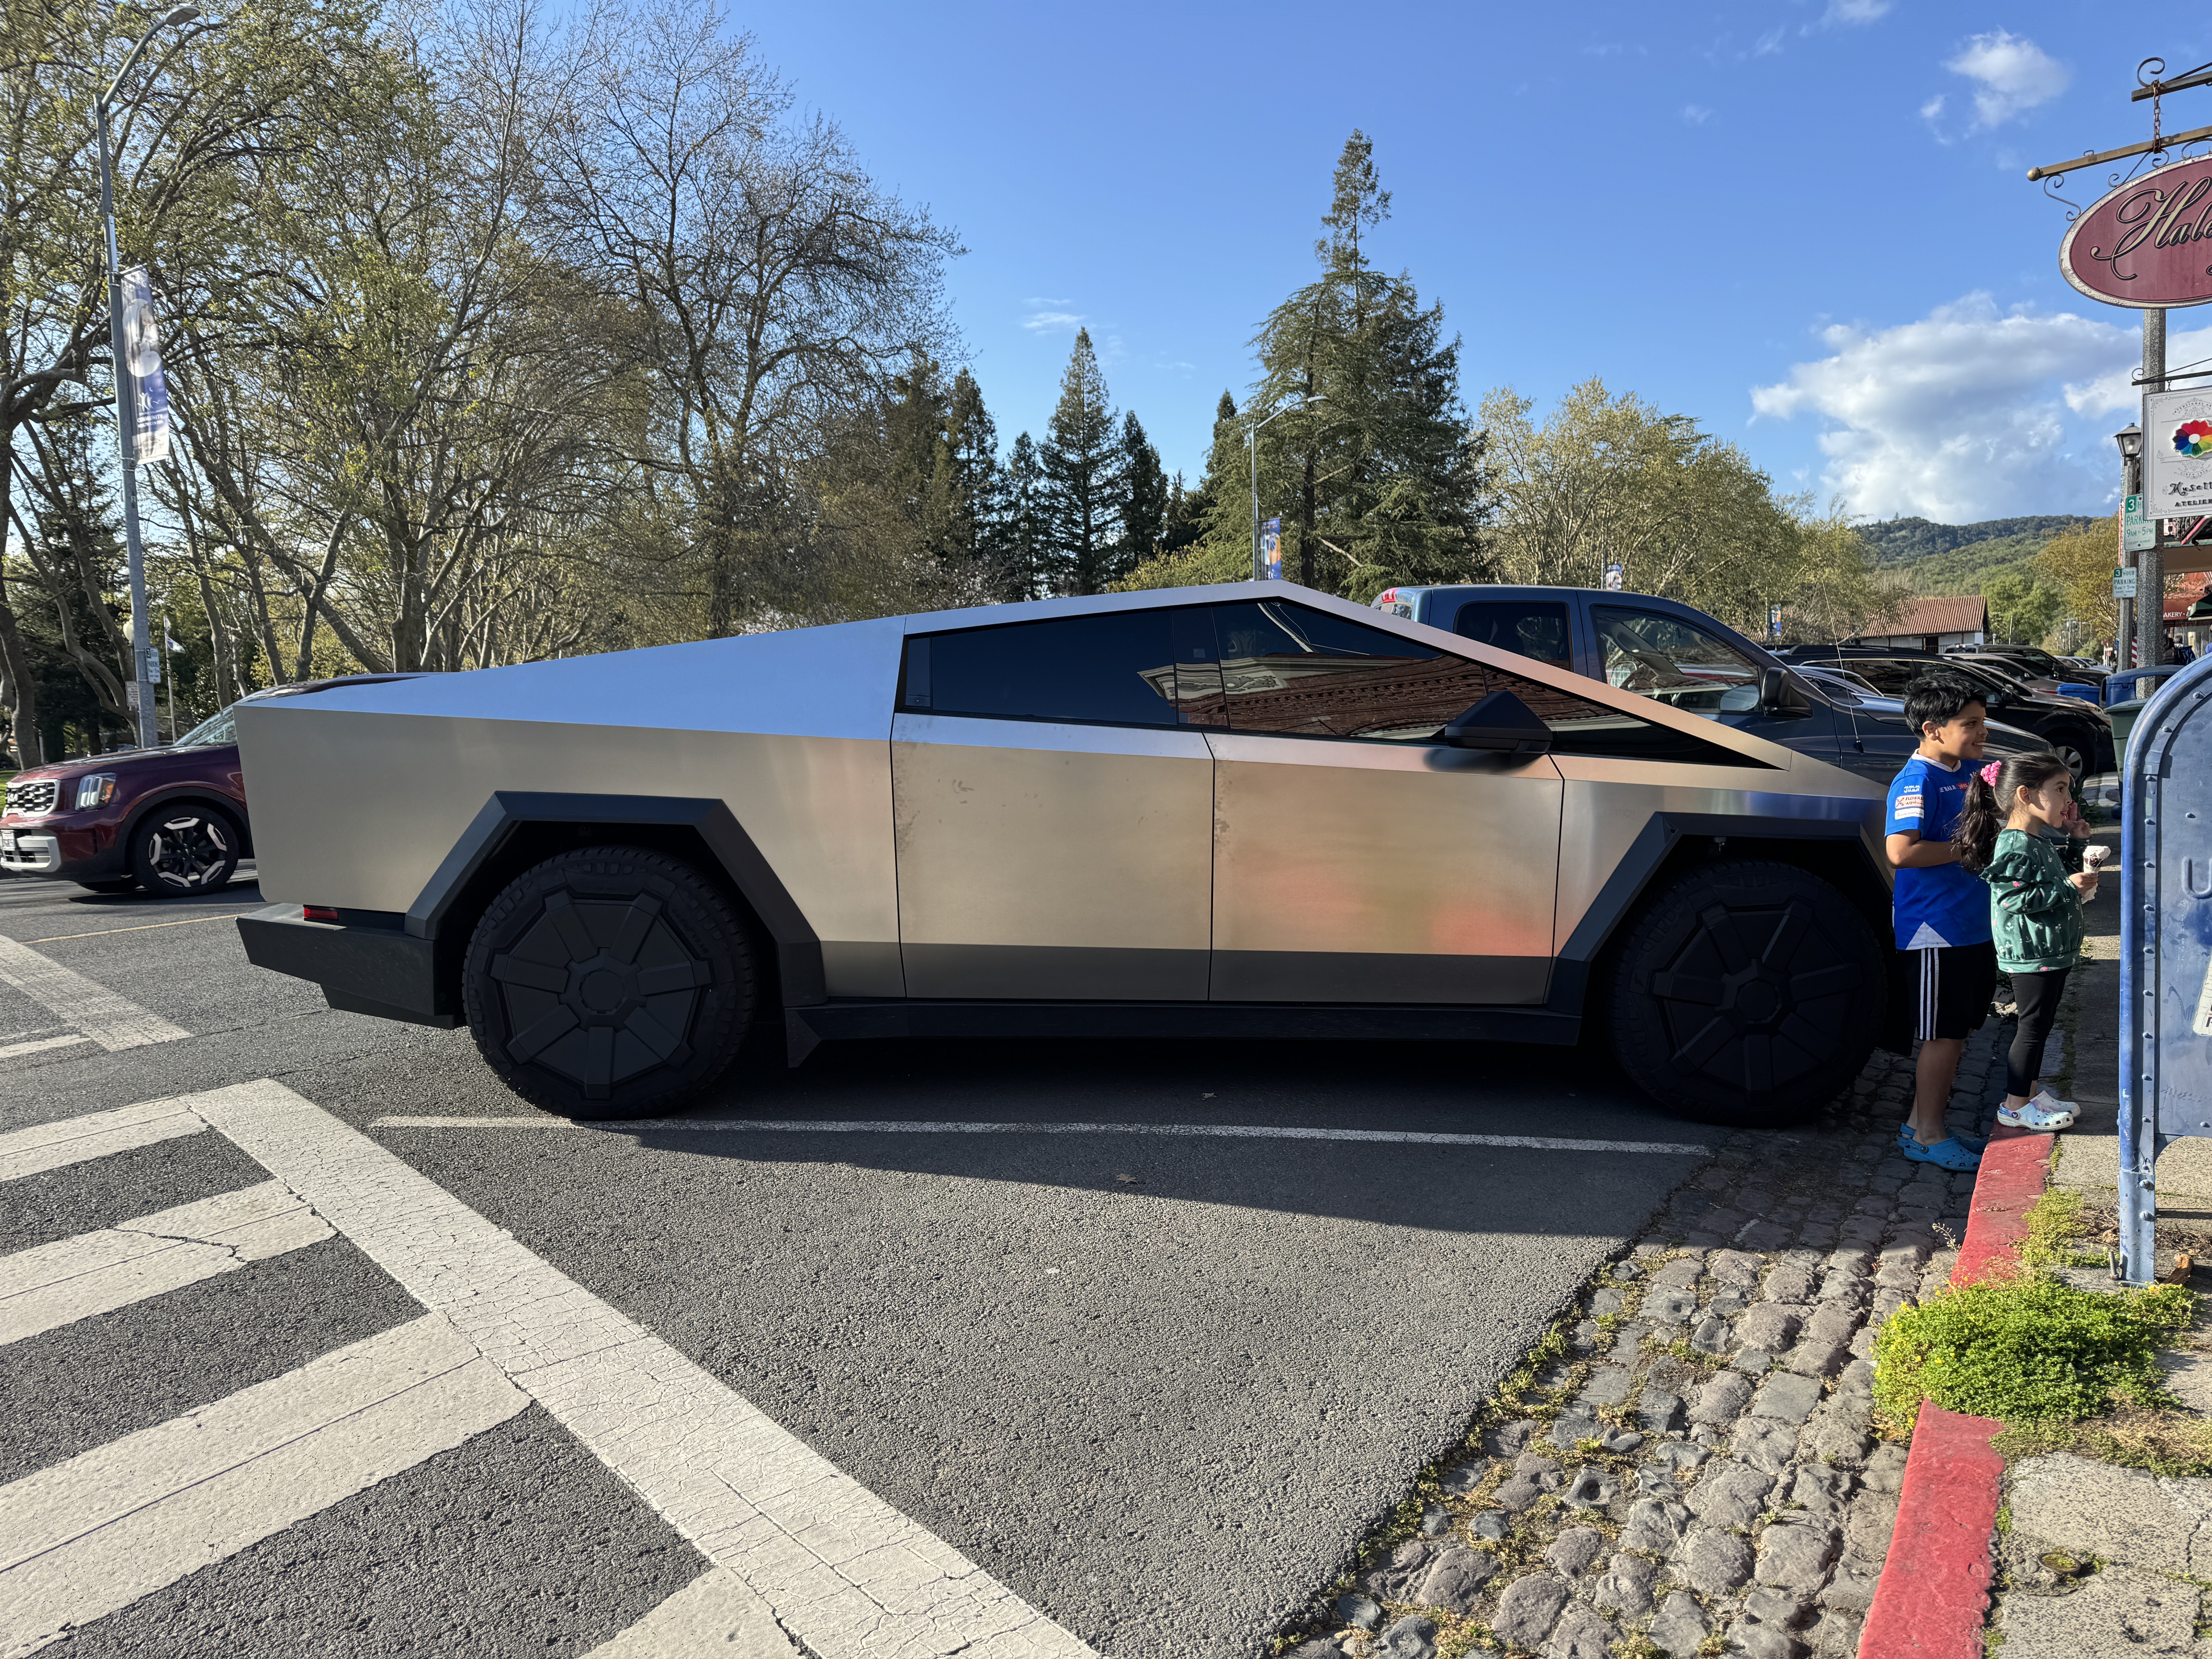
Photo: Sarah Stierch / Wikimedia Commons — CC BY 4.0; 7 April 2024 archive; resized · Illustrative image.
Cybertruck looks like a commercial failure against the scale Tesla built for. That does not make the circulating claim of an exact $1.9 billion project loss a verified fact. Those two conclusions can comfortably coexist.
On 6 November, Elon Musk said Tesla would wind down Cybertruck production at Gigafactory Texas around mid-2027 to make room for more Cybercab production. Reuters corroborated the announcement, while noting that a move elsewhere versus complete discontinuation remained unclear.
A reply by Ben McCombe in the screenshot supplied to Compound put the criticism in financial terms: capacity for 125,000 trucks a year, roughly 70,000 sold, $2 billion of research and development, just $100 million of gross profit and a $1.9 billion loss. The sales argument has substance. The profit calculation needs much more scrutiny.
Cover: Sarah Stierch’s photograph, Sonoma, California, 7 April 2024, used under CC BY 4.0. Resized archival photograph; it does not depict the November 2026 announcement.
How many Cybertrucks has Tesla sold?
Tesla does not publish a separate worldwide Cybertruck delivery total in its quarterly operational table. For a consistent model-level series, we use Cox Automotive/Kelley Blue Book estimates of US sales.
| Period | Estimated US Cybertruck sales | Comparison |
|---|---|---|
| Full year 2024 | 38,965 | First full calendar year |
| Full year 2025 | 20,237 | Down 48.1% from 2024 |
| January–September 2025 | 16,097 | Comparable nine-month period |
| January–September 2026 | 11,586 | Down 28.0% year on year |
| Q3 2026 alone | 4,323 | Down 19.7% year on year |
Sources: Cox’s Q4 2025 report and updated Q3 2026 report. Estimates are not Tesla-reported model deliveries.
Adding 2024, 2025 and the first nine months of 2026 gives 70,788 estimated US sales. That supports the approximate scale of Ben’s 70,000 claim. It covers 33 months, excludes the late-2023 launch period and is neither a worldwide lifetime count nor a full three-calendar-year total.
The trend is more revealing than the cumulative number. A new manufacturing programme normally needs volume growth to spread its development and factory costs. Here, the first full year’s estimated US sales were followed by a near-halving, then another decline on a comparable nine-month basis.
There is a fair counterpoint: Cox estimates the overall US EV market fell 30.3% in the first nine months of 2026. Cybertruck’s 28.0% decline was slightly smaller. Its 2026 weakness therefore cannot all be attributed to this particular product. But the damage began earlier: in 2025, Cybertruck fell 48.1% while the overall US EV market fell only 2.0%.
What does a 125,000-truck factory tell us?
Tesla’s Q3 2026 shareholder update lists more than 125,000 vehicles of installed annual Cybertruck manufacturing capacity in Texas. That supports the broad capacity claim, with an important qualification: installed capacity is not actual output, a sales forecast or proof that a factory can sustain that rate immediately.
Annualising the nine-month US sales estimate gives 15,448 trucks: 11,586 divided by nine, multiplied by twelve. That is 12.4% of a 125,000-unit benchmark. It is a scale comparison, not a forecast or a measured factory-utilisation rate: US sales exclude exports, and production differs from deliveries because inventory changes.
Tesla’s worldwide figures provide another boundary. The entire Other Models category delivered 8,295 vehicles in Q3 2026, down from 12,364 in Q2. Cybertruck is only part of that category. Calling all 8,295 “Cybertruck sales” would overstate what Tesla actually disclosed.
The economic concern is straightforward. Tooling, factory space and engineering resources must earn a return. When volumes are small, fixed manufacturing costs are spread across fewer vehicles. Price cuts may stimulate demand but can also reduce the contribution available to recover those costs.
This does not prove every truck was sold at a loss. It does explain why a product can be appealing to its owners and still disappoint the shareholders who funded its industrial scale.
Did Cybertruck really lose Tesla $1.9 billion?
We could not substantiate the claimed $2 billion of Cybertruck-specific R&D or $100 million of cumulative Cybertruck gross profit from the Tesla disclosures reviewed. Neither should be presented as an audited project total.
| Claim in the reply | What the evidence supports |
|---|---|
| Capacity for 125,000 per year | Tesla lists installed annual capacity above that level. |
| About 70,000 sold | Close to 70,788 estimated US sales from January 2024 to September 2026; scope matters. |
| $2bn spent on R&D | Unverified project-specific amount. |
| $100m gross profit | Unverified cumulative model-level amount. |
| $1.9bn net project loss | Arithmetic based on the two unverified inputs, not an established Tesla result. |
If the two financial inputs were correct, $100 million minus $2 billion would indeed equal negative $1.9 billion. The subtraction is easy; establishing comparable, complete inputs is the difficult part.
Gross profit deducts the cost of sales from revenue. It is not net income or free cash flow. R&D and other operating expenses sit elsewhere in the income statement. Factory investment also differs from an expense recognised immediately: some capital costs reach earnings over time through depreciation.
A credible project return calculation would need consistent periods, properly allocated development and operating costs, capital expenditure, working capital, warranty obligations and any residual or reusable asset value. Deducting factory spending and then also deducting the same investment through depreciation would double count it. Ignoring both would exaggerate returns.
Tesla did report that Cybertruck achieved positive gross margin for the first time in Q3 2024, in its shareholder update. That is evidence against assuming the vehicle never covered its cost of sales. It does not establish cumulative profitability, the size of that margin, or whether development costs were recovered.
How much profit would each truck need to generate?
We can test Ben’s implied investment hurdle without treating it as fact. Assume, purely for illustration, that $2 billion of development spending must be recovered. The table shows the vehicles needed at different average gross profits per truck.
| Assumed average gross profit per truck | Vehicles required to cover assumed $2bn |
|---|---|
| $5,000 | 400,000 |
| $10,000 | 200,000 |
| $20,000 | 100,000 |
Method: $2 billion divided by assumed gross profit per vehicle. These are scenarios, not Tesla margins or forecasts. They exclude additional overhead, financing, taxes and the timing of cash flows; this is not a complete project break-even model.
Across 70,000 hypothetical vehicles, recovering that assumed $2 billion would require about $28,571 of gross profit per truck before those additional costs. Ben’s assumed $100 million of cumulative gross profit would instead imply about $1,429 per truck and recovery of only 5% of the assumed development outlay.
This explains why his argument is powerful if its inputs hold. It also explains why the inputs cannot be waved through. A small change in lifetime volume or profit per vehicle can shift project economics by hundreds of millions of dollars.
Could Cybercab make the investment worthwhile?
Reuters also reported Cybertruck lead engineer Wes Morrill’s view that the truck served as a technology development platform whose work carries into Cybercab. That is a plausible route to recovering value, not a quantified financial return.
Reusable engineering, supplier expertise and manufacturing knowledge can reduce the cost or risk of subsequent products. A discontinued vehicle can leave behind useful assets. But attaching an unspecified “innovation benefit” to a disappointing programme is not enough to prove it was a good investment.
For shareholders, the test is whether those benefits produce identifiable savings, faster launches, higher margins or profitable revenue elsewhere. They should be credited once, with evidence, rather than used as an unlimited justification for spending.
The decision to wind down production must also be judged separately from the original investment. Money already spent is a sunk cost. If factory space can earn a higher future return producing Cybercabs, reallocating it may be sensible even if Cybertruck itself failed commercially. Conversely, moving the space does not prove Cybercab will deliver that return. Demand, operating costs and execution still have to validate the new allocation.
Our verdict: commercial failure, exact financial loss unproven
As a high-volume pickup programme, Cybertruck has failed to justify the scale of the capacity installed for it on the evidence available. Declining US sales and the announced Texas wind-down make a strong case for calling it a commercial disappointment. That is our assessment, rather than a claim that Tesla has published a full programme profit-and-loss account.
As a technology investment, the outcome remains harder to measure. Reuse could salvage meaningful value, but the benefit has not been quantified here. Positive gross margin in one quarter is not proof of lifetime success; a viral loss calculation is not proof of an exact lifetime loss either.
For TSLA investors, the next question is whether management allocates the released resources more productively. Follow the broader business through Tesla’s stock and earnings report, our Tesla cash-flow analysis and the Roadster’s potential economics.
Research checked on 6 November 2026. Financial figures are in US dollars. Sales estimates stop at September 2026; the mid-2027 wind-down is a future plan. This is company analysis, not a recommendation to buy or sell Tesla shares.