Revolut Faces a Year of Italian Supervision. What Does That Mean for Its Growth?
A Milan court ordered one year of oversight of Revolut's Italian bank operation. The financial question is whether compliance remediation can keep pace with international expansion; the bank itself faces no criminal investigation.
 Wealth / The Compound journal
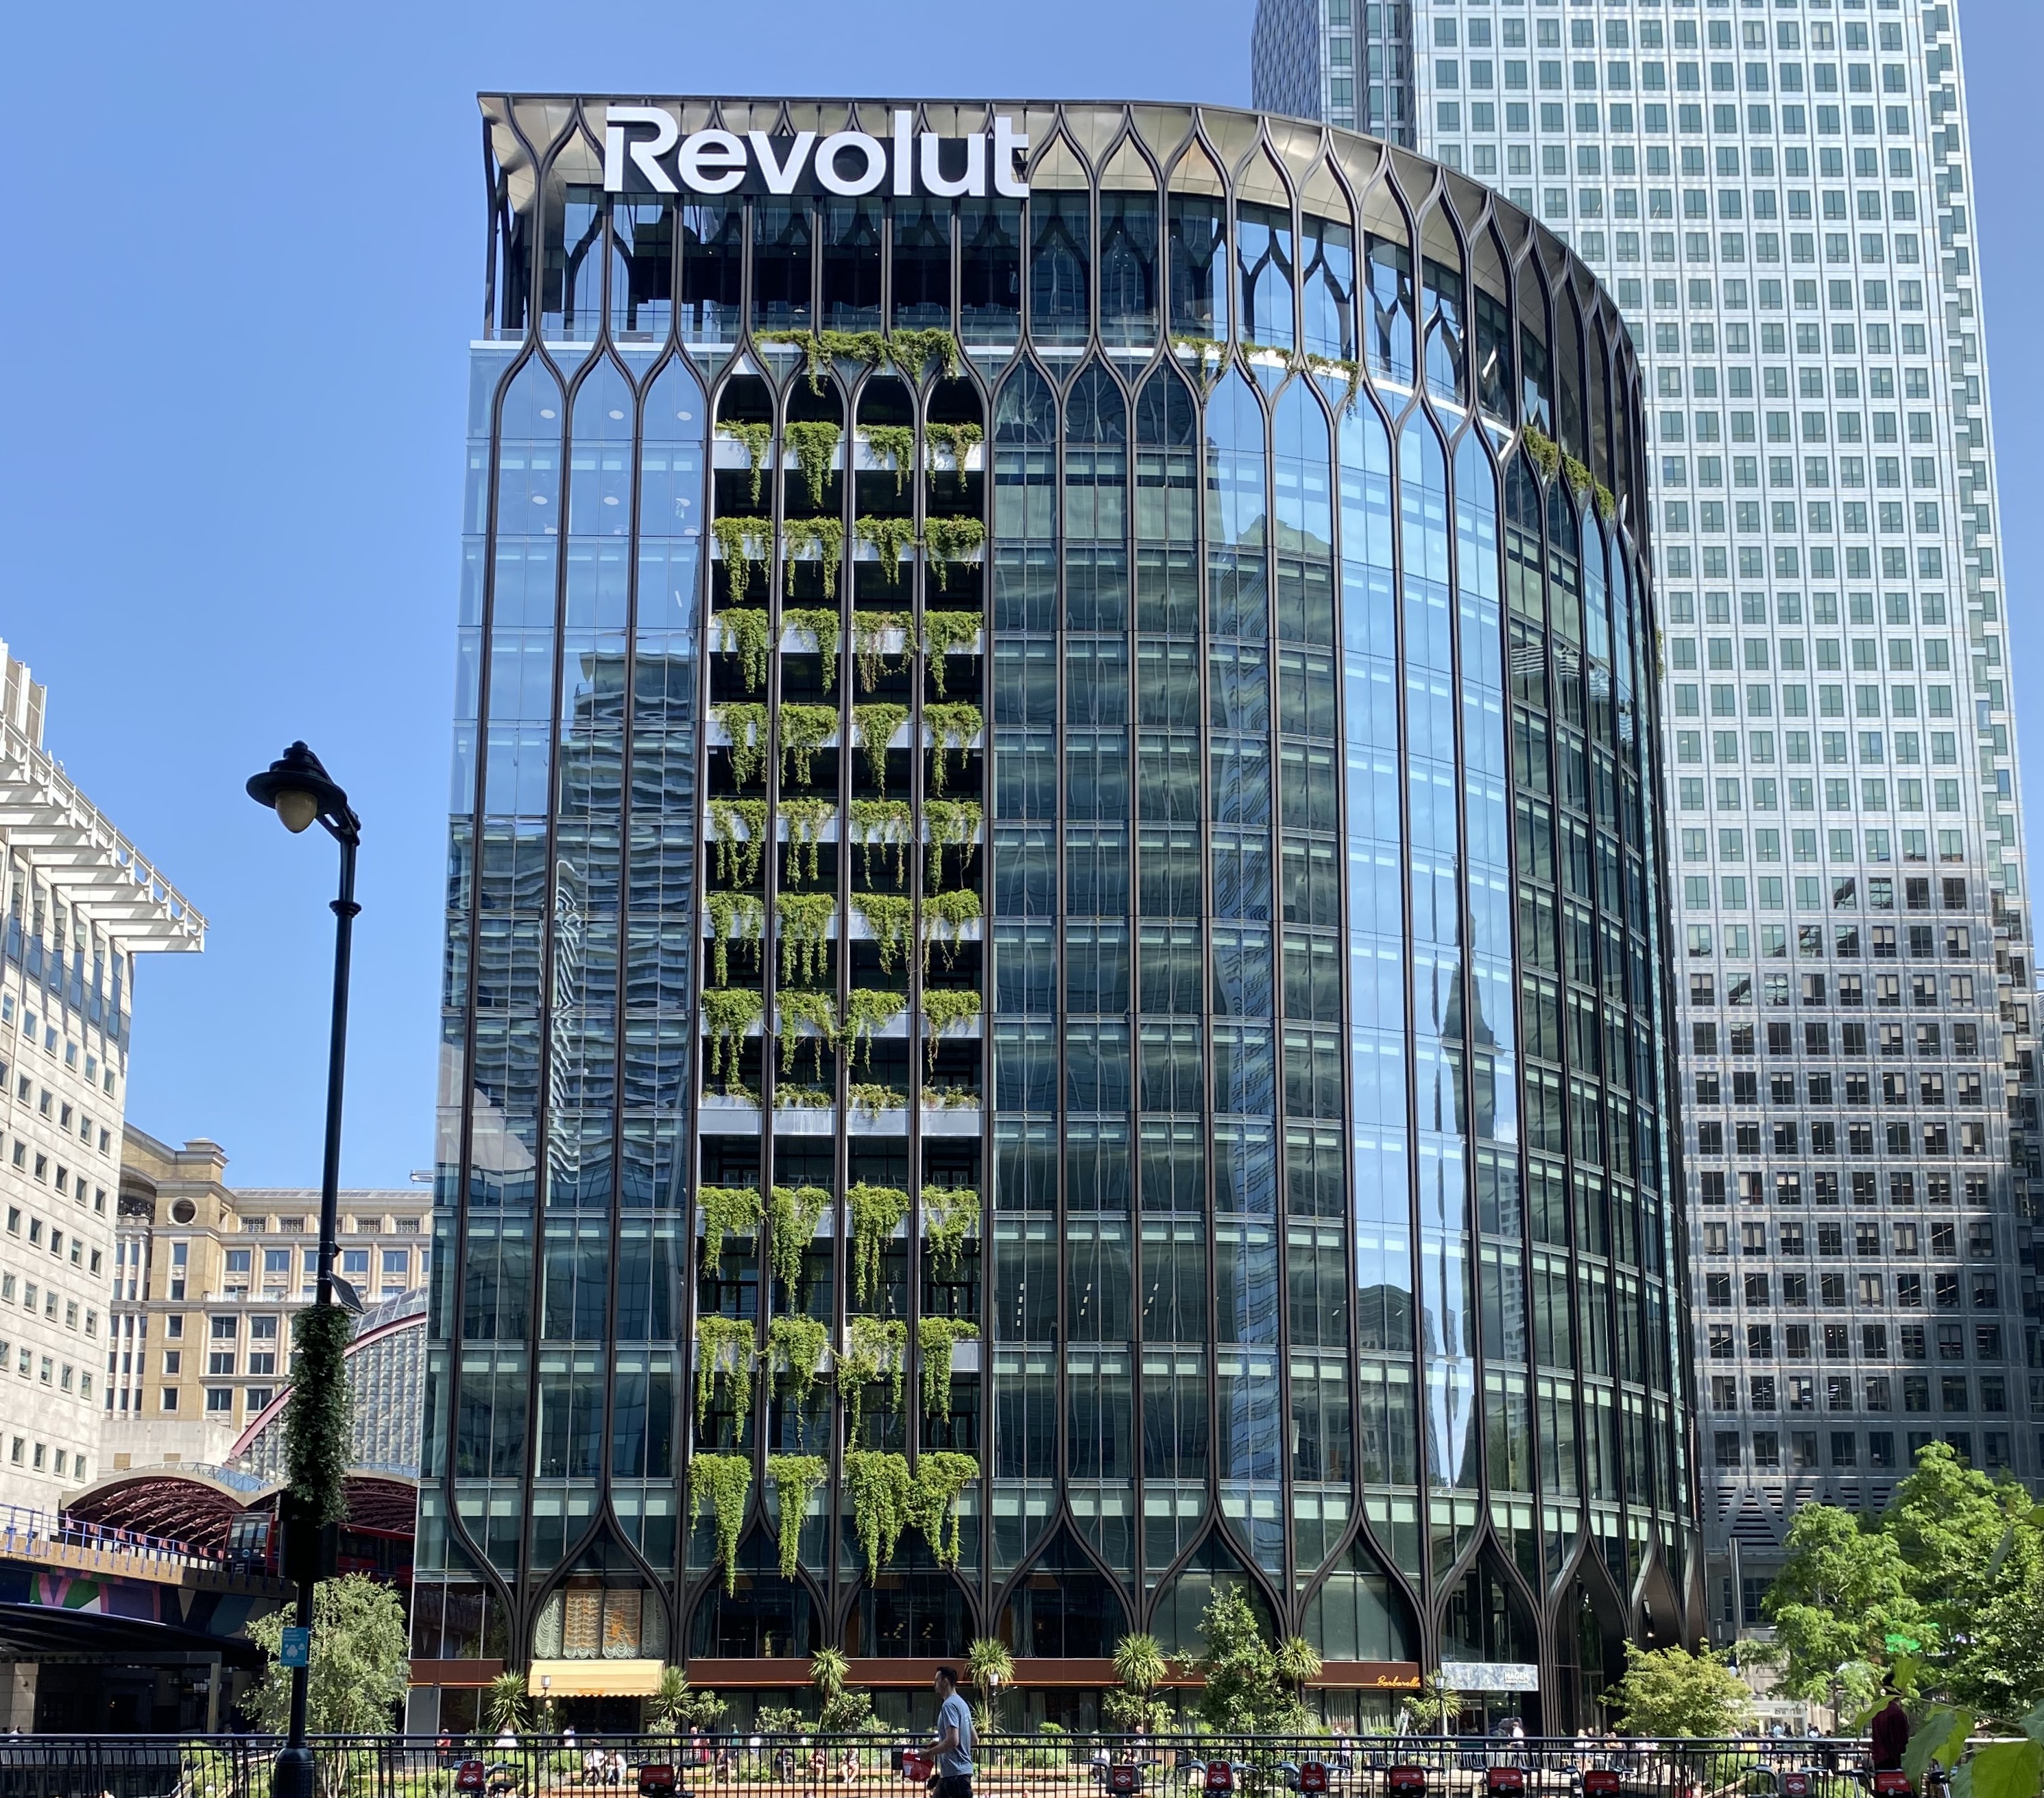
Photo: Boubloub / Wikimedia Commons, CC0 1.0 public-domain dedication; 19 June 2025, adapted archival crop · Illustrative image.
For a fast-growing bank, internal controls are not a separate concern from growth. They are part of the infrastructure needed to sustain it. A Milan court’s one-year supervision order affecting Revolut’s Italian operation tests that principle at a time when the group is expanding internationally. The commercial implications depend on the scale and effectiveness of remedial work, not on treating allegations as a quantified loss or a final criminal judgment.
On 16 November 2026, Reuters reported that a Milan court placed the Italian branch operated by Lithuania-based Revolut Bank UAB under judicial administration for one year following findings described by the court as serious anti-money-laundering control deficiencies. The court’s 39-page ruling was reviewed by Reuters; the complete ruling was not independently obtained for this article. The distinction matters: this analysis attributes its legal particulars to Reuters’ reporting of that ruling.
Revolut itself is not under criminal investigation, Reuters reported, and the oversight is confined to its Italian operations, without interruption of retail or commercial services. Revolut said it would cooperate fully with the authorities and emphasised its investment in controls, transaction monitoring and compliance teams.
What the Italian court actually ordered
According to Reuters’ account of the order, the Milan court said weaknesses in the bank’s control environment enabled 24 people suspected or convicted of criminal activity to conceal financial flows totalling €41.9 million between 2021 and 2026. The report says rival institutions submitted 265 suspicious-transaction reports concerning those individuals while Revolut Bank UAB submitted none.
Those are allegations and judicial findings as described by Reuters, not proof that Revolut earned €41.9 million, lost that sum or must pay a fine of that size. They also do not establish that all transfers were criminal proceeds. Treating a financial-flow figure as a penalty, bank revenue or shareholder loss would materially mislead readers.
Reuters says two judicial administrators have been appointed to oversee the Italian operation. The bank is to implement a 15-point remediation plan, appoint an internal liaison within five days, and submit a corrective action plan within 60 days. The administrators must report on progress, with an initial report due within 30 days and a more comprehensive assessment within 90 days. These timelines are reported court requirements, not evidence that the measures have already been completed.
Why this is different from a fine or a shutdown
Judicial administration is intended here as a preventive compliance measure, according to Reuters’ account, rather than a blanket suspension of banking services or a criminal conviction of the company. It can still demand considerable management attention because formal oversight extends beyond issuing a policy memo.
Effective repair may require stronger customer due diligence, transaction-alert thresholds, investigation staffing, training, escalation procedures, data retention and independent validation. A monitoring system that detects more suspicious behaviour may at first produce more false positives and more manual reviews. Management must improve both detection quality and investigation capacity.
An important investment question is whether remediation reveals a local implementation failure or broader weaknesses that require expensive group-wide changes. A court order concerning Italy does not, by itself, prove that customers or regulatory practices in Ireland or every other market are affected in the same way.
The expansion economics of controls
International financial services can grow customer accounts quickly, but compliance work scales with customer complexity and transaction patterns rather than user count alone. Certain risk checks can be automated. Others require qualified people, case escalation, law-enforcement liaison and local legal expertise.
Consider a hypothetical monitoring queue of 120,000 alerts a year. If improved rules increase genuinely reviewable alerts by 25%, annual reviews rise to 150,000. At an illustrative 12 minutes per review, the added 30,000 reviews require 6,000 staff-hours. At a hypothetical loaded cost of €50 per hour, that is €300,000 of additional annual review capacity before technology improvements, audits or management work.
These are editorial sensitivity inputs, not Revolut alert volumes, staffing costs, loss forecasts or court estimates. Better automated triage could reduce review time, while poor controls could require far more remediation. The point is that regulatory improvement has a cost curve: more detection is not free unless the operating model improves too.
The valuation headline is a different kind of number
On 4 November, Revolut announced the completion of a fundraising process establishing a reported $115 billion valuation. The company said it served more than 80 million retail customers and described banking and licensing expansion in several markets.
That private-market valuation is not a publicly traded share price or an independently established measure of post-remediation equity value. It provides context for the market’s growth expectations, not an arithmetic basis for a precise haircut due to one regulatory action.
A stronger assessment would examine any updated contingent liabilities, supervisory costs, incremental compliance spending, customer retention, account restrictions and banking-licence progress after the order. The public material reviewed does not allow those figures to be reliably quantified.
What Irish customers should and should not infer
Revolut provides services across Europe through regulated entities and local arrangements. Reporting about its Italian branch should not be automatically translated into a claim that Irish customer balances have become unavailable, that Revolut’s Irish operations were placed into administration or that the bank lost its licence. Reuters specifically reports that services continue and the measure is limited to Italy.
That does not make the issue irrelevant. A growing banking group’s compliance reputation may influence regulators, partners and customer trust across borders. Consumers can monitor the provider’s official notices and the regulators responsible for their particular account, rather than extrapolating from an unrelated jurisdiction.
The episode also differs from Revolut’s newly reported joint investment accounts in Ireland. One is a retail product development; the other concerns the standards required to supervise financial-crime risk. Combining them into a claim about product eligibility or Irish tax treatment would be inappropriate.
Four milestones that will make this story clearer
The next useful evidence will be whether Revolut satisfies the court’s early liaison and action-plan deadlines, what the administrators’ reports establish, whether the Italian authorities announce further findings, and how the group updates investors on any costs or other restrictions. The bank’s own statements and independently documented supervisory decisions matter more than speculation about immediate licence loss.
For private-company investors, the deeper lesson is that a fast-growing fintech’s value depends on its ability to scale customer trust and control quality alongside accounts and payments. This is a material oversight development, but it is not yet a disclosed financial loss figure or proof of group-wide failure.
Read the Revolut private-company profile and our earlier analysis of Revolut’s payment partnership with Uber for distinct dimensions of the business.
Research checked 18 November 2026. Court order details are attributed to Reuters’ 16 November report; the underlying court document was not independently reviewed. Hypothetical staffing calculation is not company data. Cover: Boubloub, Wikimedia Commons, CC0, June 2025 archival photo of the London head office, unrelated to the Italian proceedings.