ECB Holds Rates as Lagarde Announces Departure: What It Means for Your Money
The ECB has held rates as Christine Lagarde announces her February departure. What the decision means for Irish mortgages, savings and investors.
 News / Wealth
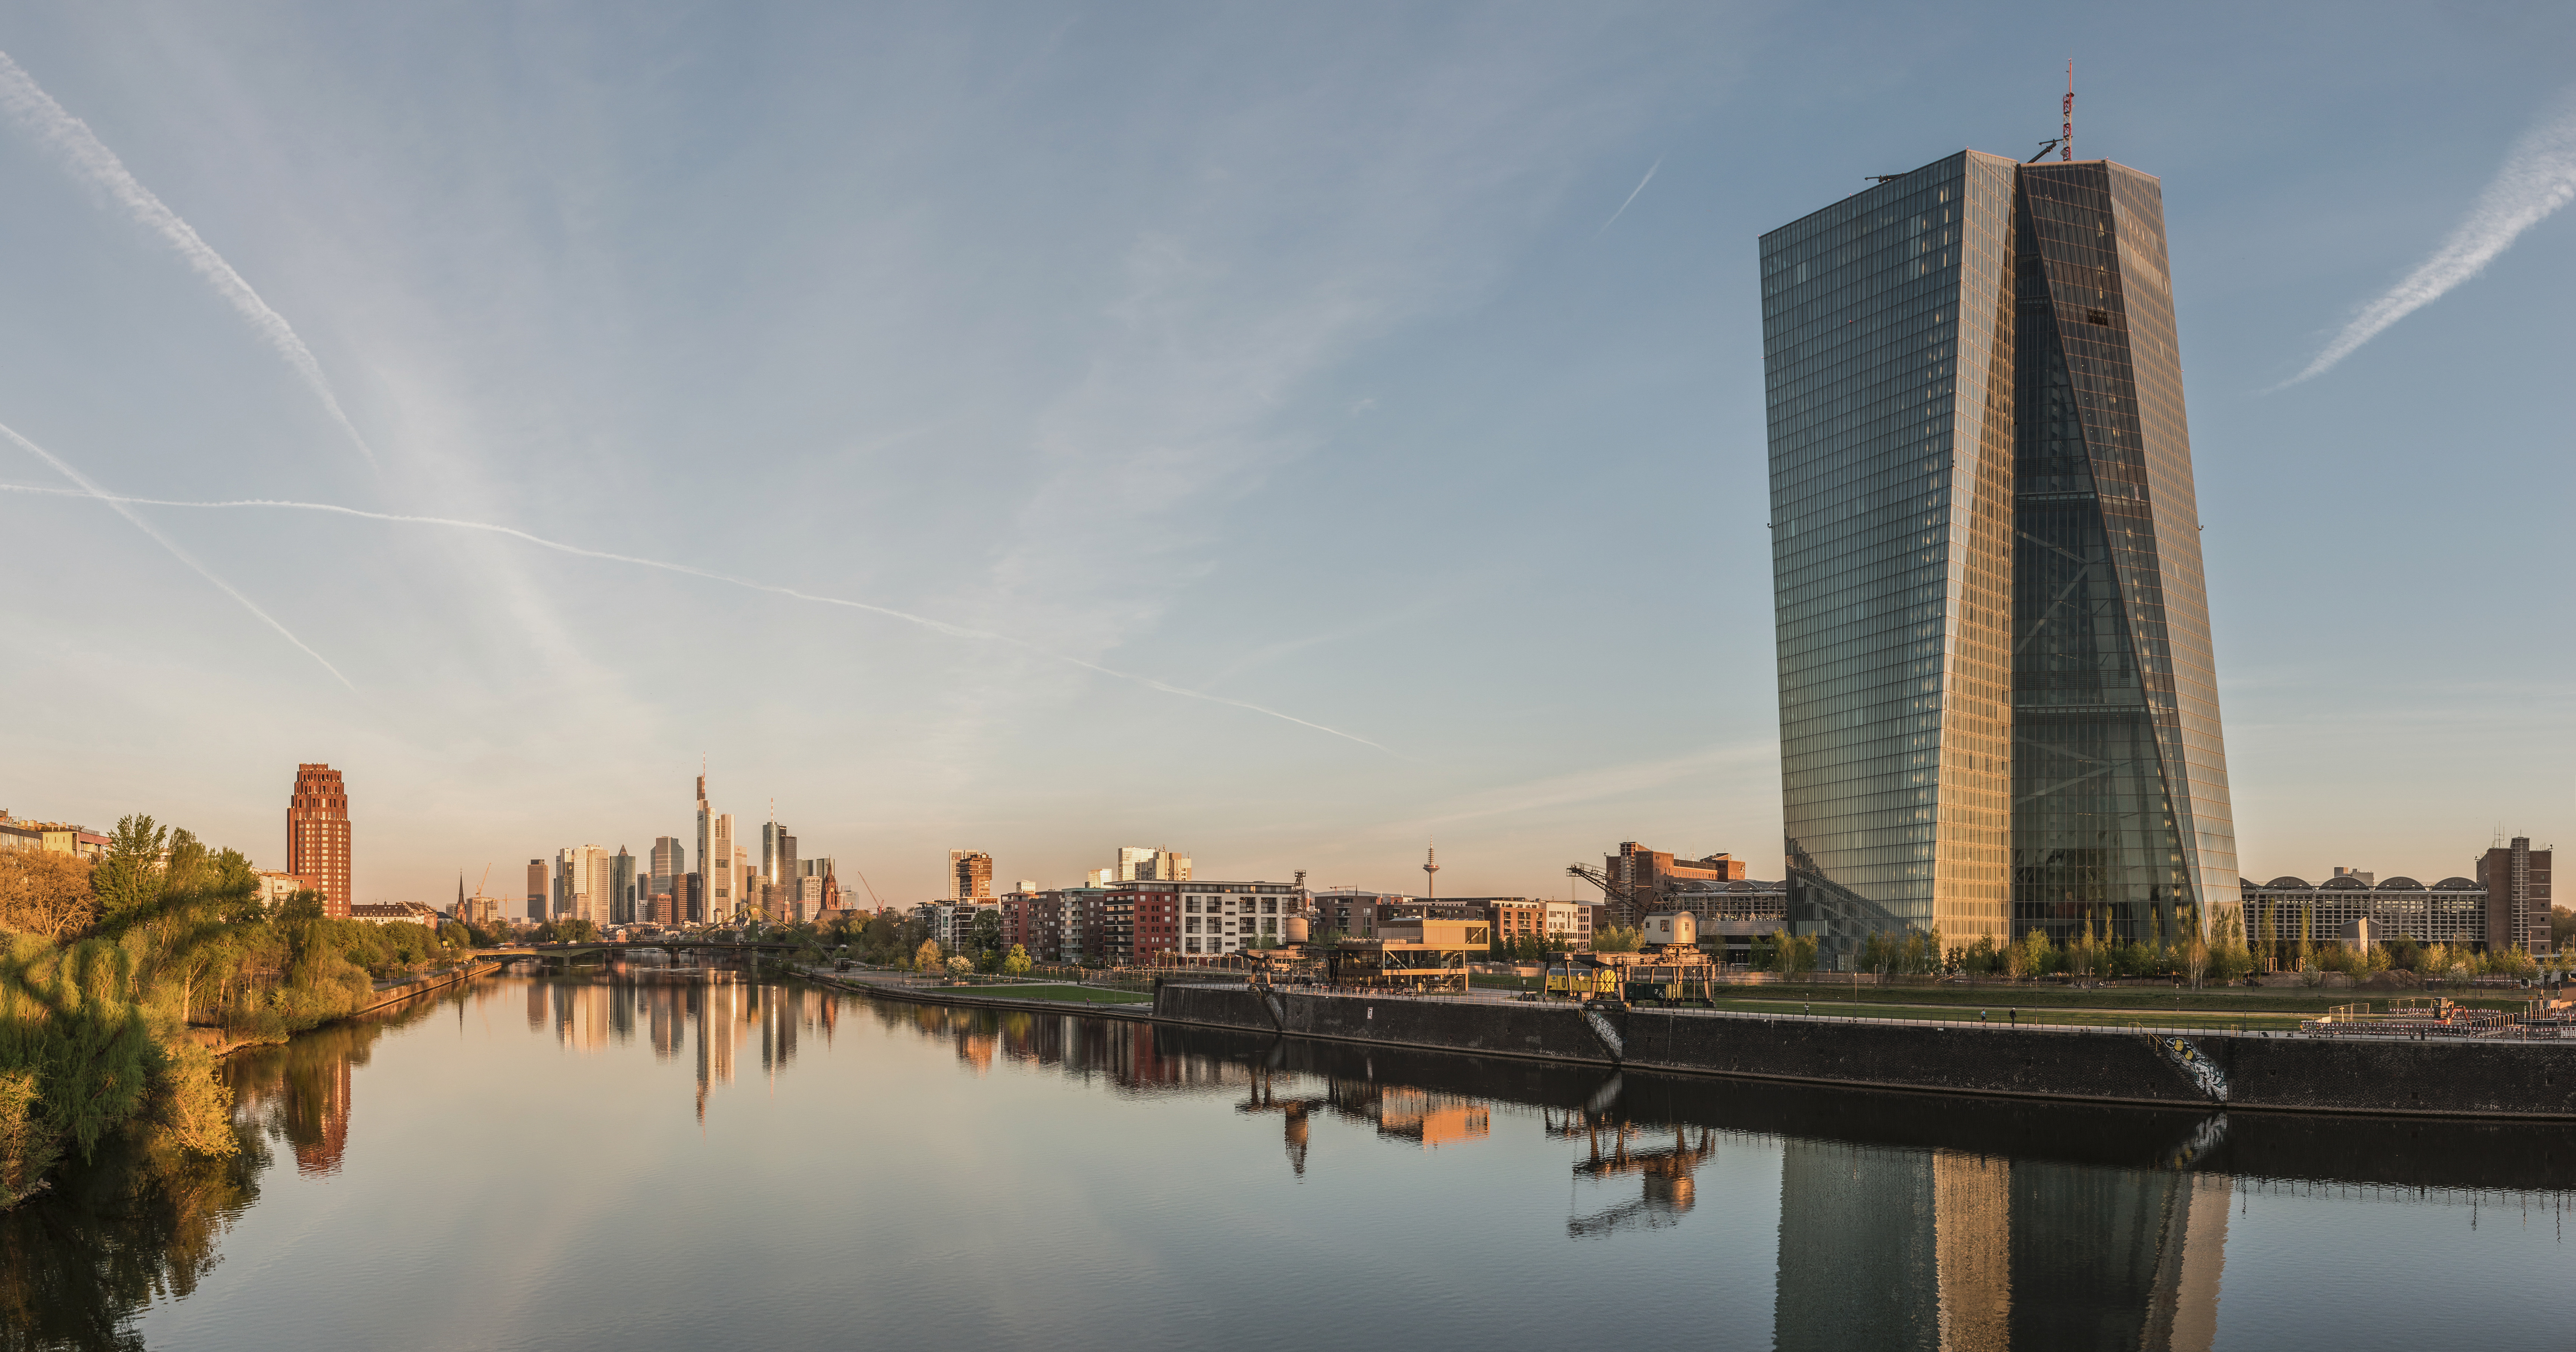
Photo: Daniel Vorndran / DXR / Wikimedia Commons, CC BY-SA 4.0. Archival photograph: 22 April 2015. Resized and cropped for display; derivatives under CC BY-SA 4.0. · Illustrative image.
29 October 2026 · Compound analysis. Cover: ECB headquarters and Frankfurt skyline, 22 April 2015. Archival photograph by Daniel Vorndran / DXR, via Wikimedia Commons, CC BY-SA 4.0. Resized and cropped for display; image derivatives use the same licence.
The European Central Bank has left interest rates unchanged, on the same day Christine Lagarde confirmed she will step down as president on 7 February 2027.
For Irish households, the immediate significance is straightforward: today’s decision brings no new ECB-driven change to borrowing costs. But it offers little certainty about where rates go next. For investors, the leadership change adds another question to an already difficult outlook for inflation and growth. The rate decision and departure announcement were published separately by the ECB.
The rates remain unchanged
| ECB policy rate | Rate after the 29 October decision |
|---|---|
| Deposit facility | 2.50% |
| Main refinancing operations | 2.65% |
| Marginal lending facility | 2.90% |
These are different policy rates serving different functions. The headline deposit rate should not be confused with the main refinancing rate used by many Irish tracker mortgages.
The decision reflects competing pressures. Rising energy costs threaten to keep inflation elevated, while tighter financing conditions could weaken spending and economic growth. Raising rates can restrain demand, but it also makes borrowing more expensive.
The ECB said it would continue assessing decisions meeting by meeting. It has not committed to a future rate path. A pause today therefore does not establish that the next move will be a cut.
What changes for Irish mortgage holders?
The answer depends on the mortgage.
For tracker borrowers, the relevant ECB benchmark and the margin in the mortgage contract determine the rate. With that benchmark unchanged today, this decision alone does not trigger a new increase or reduction. Earlier announced changes may still appear in borrowers’ correspondence or repayments, depending on implementation dates. AIB, for example, said September’s increase would be applied during September and October.
For fixed-rate borrowers, the agreed rate continues for the fixed period. The more important date is when that period ends, because the replacement offer will depend on the rates available then.
For variable-rate borrowers, lender pricing matters. These rates do not necessarily move automatically or immediately with the ECB. Borrowers should distinguish a contractual tracker from a lender-managed variable rate. The CCPC’s mortgage guidance and Pepper’s explanation of tracker and variable rates explain these differences.
Irish mortgage pricing also differs from the headline policy rate. Central Bank of Ireland figures put the weighted average rate on new mortgage agreements at 3.53% in August 2026. That is a historical market average, rather than a quote available to every borrower.
For more detail, read our fixed versus variable mortgage guide or model repayments with the mortgage calculator.
Savers should look at their own account
An ECB deposit rate of 2.50% does not mean a bank must pay customers 2.50% on their savings. Policy rates influence deposit pricing, but banks set the rates offered to customers, as the ECB’s explanation of monetary transmission describes.
The practical comparison is between actual accounts: the interest paid, access restrictions, charges and any conditions attached to the advertised return.
For illustration, €20,000 earning 1% produces €200 in gross annual interest. At 2.5%, it produces €500. That €300 difference assumes the balance and rates remain unchanged for a full year, before tax and fees.
Neither figure is a current product recommendation. The example shows why checking an account’s terms can matter more to a saver’s immediate finances than following every central-bank headline.
Why investors care about an unchanged rate
Markets respond to expectations as well as decisions. A central bank can leave rates unchanged while its explanation changes investors’ views of future borrowing costs, growth and inflation. Those expectations can affect bond yields, share prices and exchange rates.
Higher interest rates can put pressure on asset valuations. They also increase financing costs for businesses that need to borrow. The effect differs across companies, depending on their debt, refinancing needs and ability to generate cash. The ECB explains these channels in its monetary transmission overview and discussion of interest rates and asset values.
For someone researching a company, this suggests useful questions: how much debt falls due soon, how much carries a floating rate, and how comfortably does operating cash flow cover interest payments?
Those questions help translate a central-bank announcement into business analysis. The headline alone cannot establish whether a particular share is attractively priced. Our investing in Ireland guide covers the broader decisions behind building an investment plan.
Lagarde’s departure creates a transition, not a confirmed policy shift
The ECB has confirmed that Lagarde will leave on 7 February 2027. Her successor will be appointed by the European Council through the treaty nomination process. The departure announcement does not name a replacement.
A change in president matters for leadership and communication. But today’s interest-rate decision was taken by the Governing Council, and the ECB reiterated its medium-term inflation target of 2%. It would be premature to treat the departure itself as evidence that rates will fall or rise.
Compound’s reading is that the leadership story and the interest-rate outlook deserve separate attention. One concerns who will lead the institution; the other depends on inflation, economic conditions and collective policy decisions.
For households and investors, the useful response is to examine the exposures they can measure: mortgage reset dates, the return on cash, and the borrowing needs of the businesses they own. Those remain relevant whichever name appears on the next ECB announcement.