AIB Cuts Four-Year Fixed Mortgage Rates by Up to 0.35%: What You Could Save
AIB has cut its higher-value four-year fixed mortgage rates to 3.15%-3.25%. See who qualifies, the before-and-after rates and what a €350,000 borrower could save.
 News / Wealth
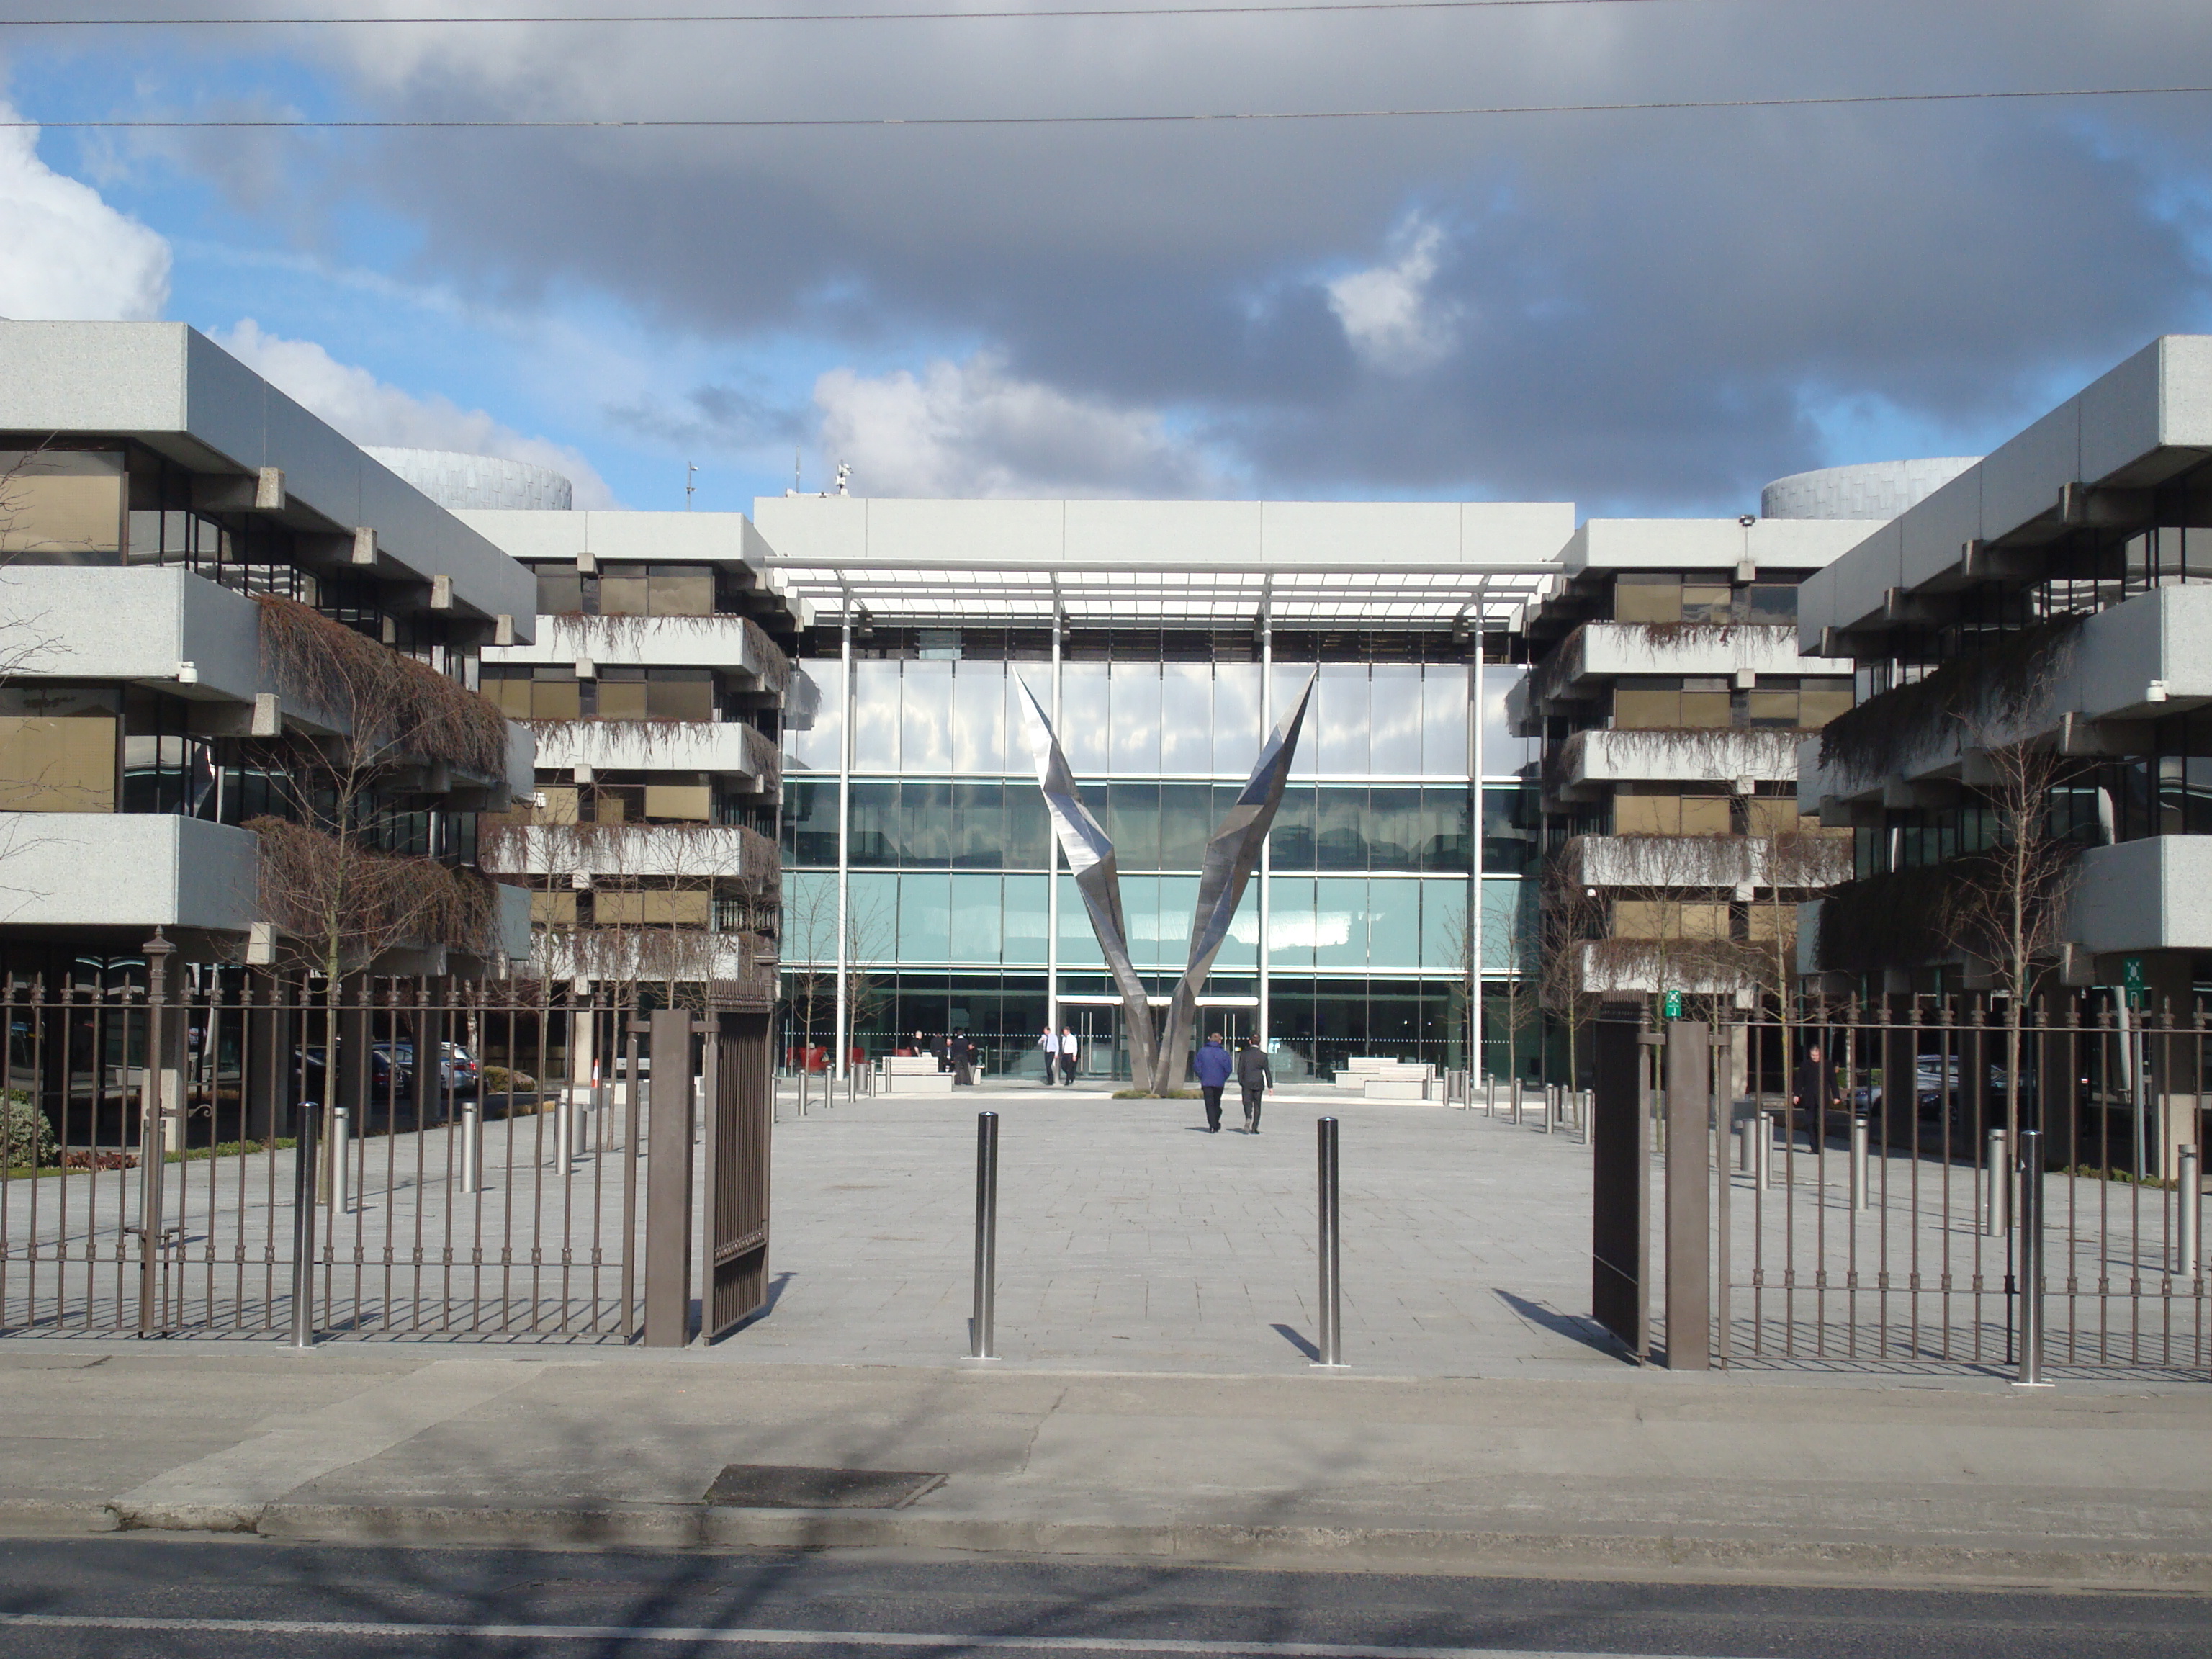
Photo: DubhEire / Wikimedia Commons (2010 archival photograph, CC0 1.0) · Illustrative image.
16 October 2026 · Mortgage news · Cover: AIB Bank Centre, Dublin 4, photographed in February 2010 by DubhEire (CC0 1.0, Wikimedia Commons). Archival image, not a photograph of today’s announcement.
AIB has reduced its higher-value four-year fixed mortgage rates by up to 0.35 percentage points, with new rates available immediately to eligible new and existing customers borrowing at least €250,000.
The cut is particularly relevant to borrowers whose homes do not qualify for AIB’s green mortgage rates. It comes despite two European Central Bank rate increases this year, showing that individual lenders’ mortgage pricing does not always track ECB moves.
AIB’s new four-year fixed mortgage rates
| Loan-to-value (LTV) | Previous rate | New rate | Reduction |
|---|---|---|---|
| More than 80% | 3.60% | 3.25% | 0.35 percentage points |
| More than 50%, up to 80% | 3.50% | 3.20% | 0.30 percentage points |
| 50% or less | 3.40% | 3.15% | 0.25 percentage points |
These are AIB’s Higher Value four-year fixed rates, not a reduction across every AIB mortgage. Your rate depends on eligibility and your home’s loan-to-value ratio.
How much could a homeowner save?
AIB’s example uses a €350,000 mortgage over 25 years, with a loan-to-value ratio between 50% and 80%:
| Monthly repayment | Amount |
|---|---|
| Before, at 3.50% | €1,750.82 |
| After, at 3.20% | €1,695.30 |
| Monthly saving | €55.52 |
| Annualised saving | €666.24 |
These are AIB’s published illustrative repayment figures, reported by RTÉ. The rate is fixed for four years, not the entire 25-year mortgage. Actual repayments and savings depend on the balance, remaining term and rate you are moving from.
Who can get the lower rate?
AIB says the Higher Value four-year rate is open to eligible first-time buyers, home movers and switchers borrowing at least €250,000. Existing AIB mortgage holders may also qualify if they have a sufficient outstanding balance and at least four years remaining on the term, including those on a variable rate or nearing the end of a fixed period.
The cut is not automatically passed to everyone on an existing fixed-rate contract. Borrowers contemplating an early switch should check for a possible break fee first. AIB also advertises a €3,000 cashback offer for eligible customers switching their mortgage to the bank, but cashback should be weighed against rates and overall costs.
Is it worth switching?
The advertised cut is useful, but the lowest headline rate is not necessarily the cheapest overall mortgage. Compare the total interest cost, fixed-rate period, break charges and any switching expenses before committing.
Use Compound’s Mortgage Calculator to test repayments, its Mortgage Switch Calculator to compare offers, or read Is Switching Your Mortgage Worth It in Ireland? for the key checks.
Bottom line: AIB’s rate cut could leave qualifying borrowers with more than €55 a month in their pocket on a €350,000 example mortgage. For anyone about to refix or switch, the bigger opportunity is to use this announcement as a reason to compare all available offers.
Sources: RTÉ News (16 October 2026), The Irish Times (16 October 2026), and AIB’s Higher Value mortgage terms.